Welcome to the Elders Insights' Weekly Market Summary for the week 2 to 8 November 2026. We recap what’s happened on the Australian commodity markets over the past week and influencing factors.
At a glance:
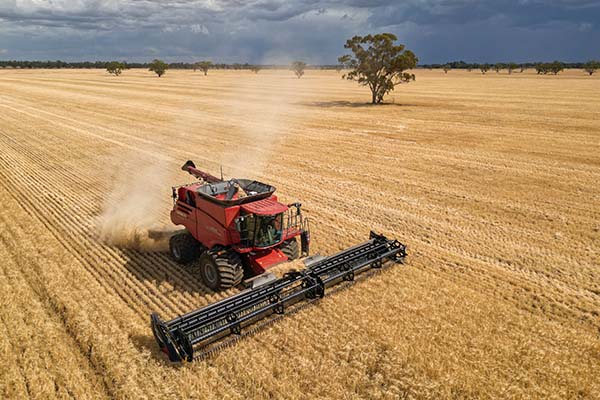
There was patchy rain of 15 to 50mm through northern parts of the Northern Territory and north-west Queensland. Storms brought rain and hail to parts of south-east Queensland, north-east and central NSW, through most of Victoria, the western half of Tassie and the far south-west of Western Australia. On the east coast, the rain further delayed harvest in the north, leading to some crop quality issues, while the hail devasted crops for some unlucky growers on the eve of harvest in parts of Victoria's Mallee. The intense storm dropped hail bigger than golf balls in some areas, sweeping across districts including Birchip, Wycheproof and Quambatook and devastated thousands of hectares of wheat, barley, lentils, canola.
Get weather forecasts for your location on Elders Weather.
The Australian dollar was swayed last week by the outcome of the US midterm elections. The Democrats won clear majorities in both the House and Senate. Markets viewed the result as potentially constraining the administration’s fiscal agenda and AI-related spending, putting downward pressure on US Treasury yields and the US dollar. As a result, the recent trend higher in the Australian dollar was reversed, with it now trading at the bottom end of its most recent range at 68.3USc, its lowest level since late March.
Cattle markets are still in the grip of grass fever with restocker cattle again registering good gains of 10 to 30c/kg liveweight (lw) but demand for other categories running out of steam as the recent hike in prices squeezes feeding and processing margins further.
Not much to report from beef export markets, with most trade participants attending the Meat Importers Council of America conference. The council stated, “We have record registrants, members and non-members, from 14 countries and a record 750+ attendees, 30 per cent (pc) higher than last year in 2025 (579), and 76 pc higher than 2024 (425)”. This provides a clear illustration of where the US beef industry is at. For years, meat imports were a side hustle for the US, but with declining production and high US domestic cattle and meat prices, the meat processing industry is now seriously exploring ways to expand the use of imported beef in both their retail and food service sectors. We should start hearing feedback filtering through from conference attendees when they land back in Australia this week.
In the November Cattle Market Update, we take a deep dive into what's driving local cattle prices and what to expect in coming months, including commentary and thoughts from our agents on the ground across Australia.
The rally in sheep and lamb prices rain out of steam this week as yardings lifted. Most categories were relatively firm except light and merino lambs which lost 40 to 50c/kg dw (dressed weight) to bring values back under $11/kg dw. There is talk that graziers struggling to get lambs to suitable slaughter weights will shear them and utilise cheap grain to get them to export weights in autumn.
View livestock for sale and our sales calendar listings.
Global grain prices marked time this week waiting for the outcome of a tri-lateral meeting in Abu Dhabi mid-week between Russia, Ukraine and the US aimed at brokering a deal to open the Black Sea export channel.
Harvest in northern NSW and southern Queensland is back underway with some test weight issues in barley (4-5t/ha) where harvest is almost done and and sprouting in wheat. Chickpea (2.5t/ha) quality is generally ok and the focus is getting chickpeas off and leaving wheat till last. There is a wide range of yields in wheat and barley with good results in golden triangle (east of Moree) but yields taper off quickly further west. Isolated storms and rain are creating havoc in places.
In western, central and southern regions of NSW there are reports of high screenings and disappointing yields in early harvested barley crops in more marginal areas. In higher rainfall, inner cropping areas, wheat is still 2 to 3 weeks off, with many crops still green with mild conditions (16 degrees in Young on Sunday) with crops needing a bit of heat to ripen.
On the west coast of South Australia (SA), barley is generally yielding 4 to 5/t/ha with up highs of 5 to 6t/ha around Ceduna, Wirrulla and Wudinna districts. Along the coast, 4 to 5t/ha is the norm. Harvest on the lower Eyre Peninsula will likely get into full swing this week. Sheep feed will be plentiful with regular showers likely to carry the feed longer into spring/summer. In the upper Eyre, early barley yields around Kimba are reportedly 4 to 5t/ha.
On the Yorke Peninsula in SA, a few started harvesting about two weeks ago north of Port Broughton, and this week, within a 20km radius of Kadina, a few have got going. Yields north of Port Broughton are not as good as they were hoping on lentils due to few warm days in early September.
Some have started reaping lentils this week on stoney & salt pan country with crops going 2.4t/ha. Expecting better country to yield 3.5 to 4t/ha if the rain stays away. Most are harvesting lentils first before barley.
In its first report for the 2026-27 WA harvest, CBH has detailed a strong and early start, with harvest in full swing in every zone, and 2.71 million tonnes (mt) delivered as of 1 Nov. The figure is close to double the 1.36mt received at the same time last year (according to Grain Central). By zone, Esperance and Geraldton are leading the way with 852,000t and 733,000t respectively, followed by Kwinana North on 622,000t and Kwinana South on 333,000t, and Albany “just getting started” with 172,000t. Canola accounts for the largest share of receivals across the state, followed by barley and wheat. The WA grower will be focussed on harvesting and delivering against canola contracts and will likely also sell barley if they need cash flow.
Local prices are generally holding up in the northern zone on the east coast, with grower selling slow as they assess grain quality and concentrate on winding up harvest. The market is generally hard to quote but may be back $5 to $10/tonne but not on significant volumes ($425/t wheat, $400/t barley Downs).
Across parts of Victoria and SA, hay quality is now in trouble due to the stop-start rain events.
In Victoria, strong demand for barley in containers continues with buyers taking advantage of the super competitive freight rates of $5 to $10/tonne on offer (compared to $30/tonne for bulk). Container packers are fully booked until 2027 and will be looking to take advantage of the new season barley once headers start to roll. Demand for November wheat remains strong in Victoria with prices holding a $20 to $30/tonne premium to new crop values. Prompt wheat $390/t and barley $310/t (the large spread explaining why barley is an easy sell).
Trade your grain at your price on the secure GCX platform.
The Australian wool market eased for a fourth consecutive week, although the pace of decline moderated and improved clearance rates suggested buyers and sellers were moving closer to a workable price level. The Eastern Market Indicator (EMI) fell 25 cents to 1,698 A¢/kg. Significantly, the pass-in rate halved from 27 to 13.6 pc, indicating greater seller willingness to meet prevailing market prices.
Learn the many ways we support wool growers.
Global cotton values registered a weekly rise on a robust US weekly export sales report. The USDA's weekly export sales report for the week ended October 29 showed net sales of 277,500 bales compared with 216,500 the previous week. Market attention will now turn to the USDA’s supply-demand and the production reports next week. Local cotton prices were unchanged at $592 and $582/bale at Dalby/Moree and cottonseed at $510/tonne.
Raw sugar fell 5.8 pc this week to 18.24US/lb, having hit a one-month low of 18.13USc/lb mid-week. Sugar is under pressure from overall energy price weakness, which tends to prompt cane mills to produce more sugar and less biofuel ethanol. Physical demand is also not great with Brazilian exports in October down 21 pc at 3.25 million tonnes.
Learn about the many ways Elders helps cotton growers.
The global hog market is in a downward spiral as declining demand intersects with increased global production. Production in China has overshot after its government provided incentives to rebuild sow numbers after the swine flu decimated herds. Producers across China have now begun liquidating herds as margins deteriorate. This has turned China from a net pork importer to an exporter, placing pressure on other global exporters. At the same time, Chinese production is increasing, however, like in many other countries, the younger generation is turning away from pork consumption. Per capita consumption among Gen Z is about 5.8lb of pork each year vs around 50lb per capita for the average US consumer. Pork is also facing pressure from plentiful supplies of chicken that’s price competitive and a ‘healthy’ choice for the consumer.
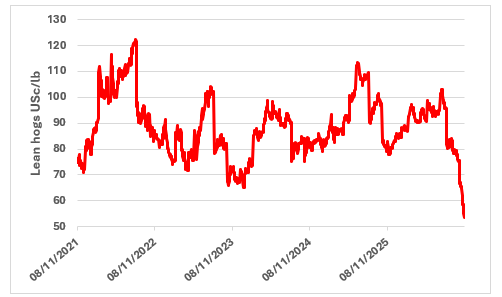 This chart shows lean hogs futures prices in USc/lb. Source: Chicago Mercantile Exchange.
The information contained in this article is given for the purpose of providing general information only, and while Elders has exercised reasonable care, skill and diligence in its preparation, many factors (including environmental and seasonal) can impact its accuracy and currency. Accordingly, the information should not be relied upon under any circumstances and Elders assumes no liability for any loss consequently suffered. If you would like to speak to someone for tailored advice relating to any of the matters referred to in this article, please contact Elders.